A second opinion on your portfolio.
Most families we meet already have an adviser, or manage their own investments. A second opinion is the step you would take before any major medical or legal decision: a careful look by someone who did not build the portfolio, with no obligation to change anything.
A good portfolio should be easy to explain.
Start with what the wealth is for. Then check whether what you own, what you pay and how it is managed still fit that purpose. Often the answer is that they do, and that is worth knowing. Where they do not, the gaps are usually in the same few places.
What the wealth is for
Income, growth, a business sale, the next generation. A portfolio should be built for a purpose you can state in a sentence.
What you own
Every holding, across super, personal names, trusts and companies, seen as one portfolio rather than separate accounts.
What you pay
Each layer of cost, from advice and platform fees to fund manager and transaction costs, set out in dollars as well as percentages.
How it is built
Asset allocation, concentration, overlap between funds, liquidity, and how the portfolio might behave in a market fall.
How it is managed
How decisions are made, how often the portfolio is reviewed, and whether the reporting you receive is clear.
How the pieces fit.
Most portfolios we review are sound in parts. The issues are rarely about one investment. They are about how the pieces fit together.
Several portfolios, no single plan
Accounts set up at different times, often by different people, that have never been looked at as one.
Costs that are hard to see
Fees spread across advice, platform and fund layers, so the total is rarely stated in one place.
A plan that has drifted
A portfolio that suited the family some years ago, but not the business sale, retirement or inheritance since.
When it is time for a second look.
Families usually ask for a second opinion when one of these is true.
Something has changed
A business sale, retirement, an inheritance, or the next generation becoming involved.
It is hard to explain
What you own, what you pay, or why the portfolio is built the way it is.
It has been a while
No one outside the current arrangement has looked at the portfolio for some years.
A clear view, then your decision.
We are not constrained by any one product, manager or asset class, so the review starts from what fits your family. Many families keep their existing arrangements after a second opinion. Where a change is worth making, we explain why in writing, including what it would cost to make.
One picture of everything you own
We bring your statements together into a single view, across every account and structure.
Your costs, in dollars
What you pay each year, at each layer, in one place.
Our findings, explained
We take you through what we found, in person or by video, in plain English, and answer your questions.
Your decision
There is no obligation. If you want to act, we agree the fee in writing first, then prepare personal advice for your circumstances.
Who you deal with.
You work directly with Murdoch. Where the review touches tax or legal structures, we note it for your accountant or lawyer rather than advise on it.
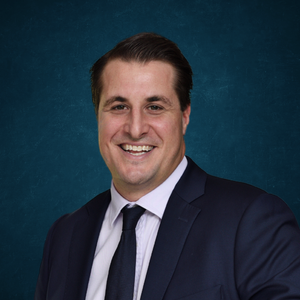
Murdoch Gatti
Founder and Private Wealth Adviser. In financial markets and wealth management since 2006. Master of Commerce (Finance) and Diploma of Financial Services (Financial Planning). Host of The Rate of Change podcast, in conversation with fund managers, economists and business leaders. You work directly with Murdoch.
Authorised Representative No. 001007979 · About York
Getting a second opinion.
The questions we are asked most often by families thinking about a second opinion on their portfolio.
What is a second opinion on a portfolio?
A review of your existing investments by an adviser who did not build them. We look at what you own, what you pay, how the portfolio is built and how it is managed, against what the wealth is for.
Is the second opinion complimentary?
Yes. The first conversation and the second opinion are complimentary and carry no obligation. If you then want personal advice, the fee is agreed in writing before any work begins.
What do I need to provide?
The most recent statement for each account, including super, platforms and any managed funds, and a sense of what the money is for. A rough picture is enough to start.
Will my current adviser know?
Not unless you tell them. We work from the statements you provide, and we do not contact your adviser, fund managers or platform without your permission.
How do I know if my financial adviser is any good?
Ask yourself whether you can explain, in a sentence, what your portfolio is for, what you pay each year in dollars, and why it is built the way it is. If those answers are clear and the reporting is regular, that is a good sign. If they are not, a second opinion can help.
What fees should I be paying?
There is no single right number. What matters is knowing the total, across advice, platform, fund manager and transaction costs, in dollars, and what you receive for it. We set that out for you as part of the review.
Should I change financial adviser?
Not necessarily. Many people keep their existing adviser after a second opinion. A change is worth considering when the portfolio no longer fits what the wealth is for, or when costs and reporting are unclear. Selling investments to move them can have costs and tax consequences, so we weigh those first and work with your accountant.
Can you review a portfolio I manage myself?
Yes. Many of the portfolios we review are self-managed, including share portfolios held directly. The questions are the same: what it is for, what it costs, and how it is built.
How are your fees set?
Fees are agreed in writing before any work begins. A first conversation is complimentary and carries no obligation. Details are in our Financial Services Guide.
General information only. This page has been prepared without taking into account your objectives, financial situation or needs. Before acting on it, consider whether it is appropriate to you in light of your objectives, financial situation and needs. York does not provide tax advice; we work with your accountant on your own position.
Three steps, at your pace.
There is no obligation at any stage, and no recommendation is made until you engage us in writing.
01 A first conversation
Twenty to thirty minutes, complimentary, to understand your family and what the wealth is for.
02 Send your statements
The latest statement for each account. We review them and prepare our findings.
03 We take you through it
In person or by video. What you do next is your decision.
Start with a conversation.
If you are considering a long-term advisory relationship, the first step is a 20–30 minute conversation to understand whether we are the right fit for you and your family.
Three short questions. An adviser will be in touch shortly after.
Which best describes you?
What would you like help with?
How should we reach you?
Leave your name, email and phone number and an adviser will contact you shortly to arrange a time.
Enter your details